
Pesky Inflation, Rising Rates, Living Longer, and Two Weddings

September 13, 2026
NEVER TO BE FORGOTTEN: I wrote this five years ago on the twentieth anniversary of 9/11:
Twenty years ago, I was driving north on the New Jersey Turnpike toward Edison, NJ for a financial planning meeting with my client Ray, a utility executive. The meeting was set to begin at 9:00. On the way, I heard a report on the radio about a plane going into the World Trade Center towers. It did not yet sound ominous. I walked to my client's office complex and asked for Ray. As I was waiting, I heard a lot of commotion and televisions playing. I heard someone say a plane just went into the second tower and they were both on fire. Ray came out, and I told him we could do this meeting some other time. "No," he said, "Let's carry on." Amazingly, as all this drama was happening, we went through Ray's financial plan. At 10:00, someone charged into Ray's office, "The South Tower just collapsed." Everyone deals with news like this in different ways. Perhaps Ray's way was avoidance, because he insisted we continue. Me? My brain did not let what I just heard compute. I thought he must have meant the radio tower or the large antenna on top of the building, not the building itself. That would be ludicrous. At about 10:30, as we were getting ready to wrap up, the same co-worker charged in, "The North Tower is down." It was only at this point that I was beginning to process what was going on. Ray and I finished that meeting and walked out in a mental fog that was quickly sharpened by our new reality. I drove south on the New Jersey Turnpike seeing a massive amount of first responders going north on the same road as I hurried to be with my family. We all have our own vivid memories of that specific point in time that we will never forget.
INFLATION: The August Consumer Price Index (CPI) rose 0.4%, and it is up 3.4% from one year ago. Energy prices were up 2.1%, and food was up 0.1%. The "core" CPI, which excludes food and energy, was up 0.3% and is up 2.4% over the past year. Earlier, the Producer Price Index (PPI) was announced, and wholesale prices in August rose by 0.4%, with rising energy prices being the primary driver. Without energy prices, the PPI was up 0.2%.
STOCKS REBOUND LATE, BUT NOT ENOUGH FOR A POSITIVE WEEK: Stock and bond investors have been fearful of a Fed rate hike. As the inflation news rolled in on Friday, coupled with last week's reports of a strong labor market, it is becoming clearer that the Fed will likely raise interest rates next week. But the clarifying inflation news didn't spook the markets. Instead, the clarity it provided seemed to calm investors, and despite wandering lower all week, a rebound of sorts occurred on Friday to stem the losses. Investors will be watching the effects of higher borrowing costs on overall corporate earnings. Corporate earnings are driving this market rally. Meanwhile, hopes of an imminent resolution of the Middle East turmoil seem to have been dashed, and that reality is settling into this market.

LONGER-TERM PERFORMANCE: Below are the annualized three-year and five-year numbers for these same indices.

THE FED: It now seems quite likely that the Fed will raise its key interest rate this coming week. Because we are now all expecting it, the act will probably not move markets much, but the guidance given by Chairman Walsh may, depending on what he says. We all wait.
EUROPEAN CENTRAL BANK RAISES RATES AGAIN: The European Central Bank raised interest rates for the second time this year. It stated that heightened inflation concerns caused the move. Europe's inflation rate rose to 3.3% in August, its highest rate in three years. Its key interest rate is still over 1.0% lower than the Fed and the Bank of England's rates.
SALES OF EXISTING HOMES: Existing home sales decreased by 2.0% in August. Rising mortgage prices slowed buying activity. The annual sales pace of existing homes has been stuck in the 4.0 million range since the end of COVID-inspired government shutdowns. The median price for an existing home decreased slightly, but is still 1.6% higher than a year ago.

SOMETHING FOR WHICH WE CAN BE GRATEFUL: Life expectancy remained rather static, and low, for centuries (see graph below). Then the industrial revolution arrived, and innovations in infrastructure, hygiene, and medicine sent lifespans rocketing upward (and still going). Many of the innovations that help fuel these increases come from companies that you may be invested it, so don't think your investment choices are meaningless or solely focused on getting you the next dollar in your portfolio. There are real companies that do valuable things, and often the ones that innovate to find ways to make your life better, and sometimes healthier, are the ones that have real long-term growth potential.

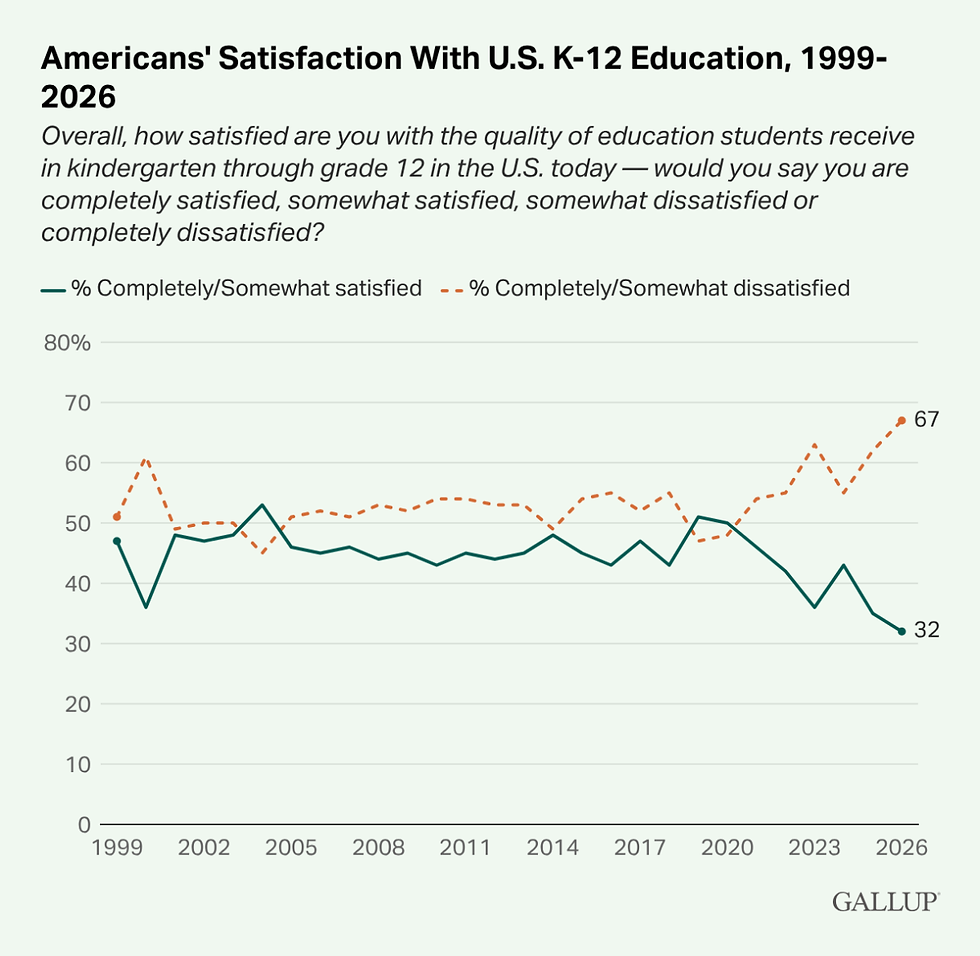
SOMETHING ABOUT WHICH WE SHOULD BE CONCERNED: As the graph below shows, the performance of students in schools of developed countries has been decreasing. When looking at the U.S., the results are also poor. According to a report published by the New York Times, the reading scores of American 15-year-olds have fallen sharply since 2022 and recently hit its lowest point in 25 years. Math scores are also slipping, but science scores have remained static for a while. Not surprisingly, Americans' satisfaction with the quality of K-12 schools has fallen dramatically. According to a Gallup poll released last week, 67% of Americans are either completely or somewhat dissatisfied with U.S. K-12 education. That is the highest percentage of dissatisfaction in the 27 years Gallup has been conducting this poll. The percentage that are satisfied dropped to 32%. In 2019, 51% were satisfied, and 47% were dissatisfied. That roughly 50-50 split was a trend going back to the turn of the century that did not vary by a lot. This downward trend is brand new. According to the U.S. Census Bureau report of 2024, the latest report we have, the average spending per year per pupil in the U.S. is $17,619.

U.S. COLLEGES: What do the following institutions in the U.S. have in common?
University of Valley Forge (Phoenixville, PA)
Labouré College of Healthcare (Milton, MA)
Anna Maria College (Paxton, MA)
Lourdes University (Sylvania, OH)
Providence Christian College (Pasadena, CA)
Sterling College (Craftsbury Common, VT)
Trinity Christian College (Palos Heights, IL)
Siena Heights University (Adrian, MI)
Hampshire College (Amherst, MA)
Modern College of Design (Ohio, for-profit)
Martin University (Indianapolis, IN)
Fontbonne University (St. Louis, MO)
Northland College (Ashland, WI)
Limestone University (Gaffney, SC)
St. Andrews University (Laurinburg, NC)
Eastern Nazarene College (Quincy, MA)
Bacone College (Muskogee, OK)
Paier College (Bridgeport, CT)
Jamestown Business College (Jamestown, NY)
Pennsylvania Academy of the Fine Arts (Philadelphia, PA)
What they all have in common is this: They are all degree-granting colleges and universities that ceased independent operations in 2025 and 2026.
NOT A RANDOM HOUSE: When Deb and I were in Maine last weekend for a wedding, we visited a house that is currently owned by one of the most famous writers on the planet. Evidently, he and his wife no longer live in the house, but it is still owned by them and he uses it for his archives and for other purposes. There are definitely clues within the picture that should help if you are trying to guess. It's a beautiful, if quirky, house.

TWO WEDDINGS IN A WEEK: Within one week, two children of two sets of very close friends of ours got married. On Friday night, we were at a more local wedding, and it was a wonderful event.

Have a great week!
Our purpose is to honor God by helping our clients see the objective, find the path, and navigate past the obstacles to a more prosperous future.

Douglas R. MacGray, J.D., C.F.P. ®
President
Stonecrop Wealth Advisors, LLC
Direct | Cell | Fax
(610) 628 4545
"“Always give your best. Never get discouraged. Never be petty. Always remember, others may hate you. But those who hate you don’t win unless you hate them. And then you destroy yourself.” Richard M. NIxon*
“Do not be overcome by evil, but overcome evil with good.” Romans 12:21 (NIV)
*In commemoration of the 250th anniversary of the United States, I am finding a quote from a president each week, in order. This is the 37th week, and Richard Nixon was our 37th president.
SOURCES:
SOMETHING ABOUT WHICH WE SHOULD BE CONCERNED: https://www.oecd.org/en/publications/pisa-2025-results-volume-i_73451bc5-en.html AND https://news.gallup.com/poll/714017/satisfaction-education-hits-new-low.aspx AND https://www.wsj.com/opinion/opinion-of-u-s-schools-hits-a-new-low-defa3d37?mod=hp_opin_pos_2
U.S. COLLEGES: https://thecollegeinvestor.com/79342/8-colleges-closing-in-2026-full-list-of-closures/, https://www.highereddive.com/news/university-of-valley-forge-in-pennsylvania-to-shutter/826661/, https://www.bestcolleges.com/research/closed-colleges-list-statistics-major-closures/, https://www.collegetransitions.com/blog/college-closures-and-mergers/, https://www.northland.edu/?s=closure, https://www.highereducationinquirer.org/2025/08/a-preliminary-list-of-private-colleges.html, https://www.2adays.com/blog/campus-collapse-college-closures-and-mergers-rock-ncaa-naia-and-beyond-update/
EUROPEAN CENTRAL BANK RAISES RATES AGAIN: https://www.wsj.com/economy/central-banking/the-ecb-just-raised-interest-rates-heres-what-to-know-c03f9bb0?mod=central-banking_more_article_pos3
STOCKS REBOUND LATE, BUT NOT ENOUGH FOR A POSITIVE WEEK: https://www.wsj.com/finance/investing/wall-street-cheers-clarity-on-fed-outlookeven-if-it-means-higher-rates-2f80fd5f?mod=stocks_news_article_pos1
SALES OF EXISTING HOMES: https://www.ftportfolios.com/Commentary/EconomicResearch/2026/9/10/existing-home-sales-declined-2.0percent-in-august
© 2026 Anno Domini, Stonecrop Wealth Advisors, LLC, All Rights Reserved *S&P 500: This is a measure of the performance of the 500 largest companies in the United States, and it a common index to track the performance of U.S. equity markets, especially the large cap markets.
*MSCI All Country World Index X US: This is a broad measure of the performance of worldwide equity markets excluding the United States.
*Bloomberg U.S. Aggregate: This is a measure of the U.S. bond markets.
Investment advisory services offered through Stonecrop Wealth Advisors, LLC, a Registered Investment Advisor with the U.S. Securities and Exchange Commission.
The information contained herein has been compiled from third party sources (see above) and is believed to be reliable, however its accuracy is not guaranteed. This newsletter is not an offer or a solicitation to buy or sell securities, and you should not construe it as investment, tax, or legal advice, or a specific investment recommendation. Any opinion included in this newsletter is our judgment as of the date of this report and is subject to change without notice.
If you want any additional information regarding Stonecrop Wealth Advisors, including management fees and expenses, you can contact us directly, or review our Form ADV Part 2 which can be found here (www.adviserinfo.sec.gov), or which we will be happy to provide to you upon request. Only God knows the future, and so while past performance can be helpful information, it is not a guarantee of future performance which could be completely different.
SDG


Comments